Class implements the bond paying fixed coupon. More...
#include <fixedIncomeBond.hpp>
Public Member Functions | |
| FixedIncomeBond () | |
| Default Constructor. More... | |
| FixedIncomeBond (Date issue_date, Date maturity_date, double principal, double coupon, InterestRate rate, CashFlowVector cash_flows, Frequency payment_frequency) | |
| Constructor. More... | |
| double | getCoupon () const |
| returns the coupon More... | |
| virtual | ~FixedIncomeBond () |
| destructor More... | |
Bond interface | |
| virtual void | valuation (const SmartPointer< ir::Curve > &curve) const override |
| bond valuation More... | |
| virtual void | valuation (const SmartPointer< ir::Curve > &curve, const SmartPointer< ir::Curve > &) const override |
| bond valuation More... | |
| virtual double | prize (const SmartPointer< ir::Curve > &curve) const override |
| prize bond More... | |
| virtual double | prize (const SmartPointer< ir::Curve > &curve, const SmartPointer< ir::Curve > &) const override |
| prize bond More... | |
| virtual double | getPrincipal () const override |
| returns the bond's principal More... | |
| virtual Date | getDate () const override |
| returns the bond's maturity More... | |
| virtual FixedIncomeBond * | clone () const override |
| virtual copy constructor More... | |
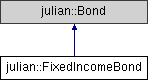
 Public Member Functions inherited from julian::Bond | |
| Bond () | |
| constructor More... | |
| virtual | ~Bond () |
| destructor More... | |
Private Attributes | |
| Date | issue_date_ |
| Bond's issue date. More... | |
| Date | maturity_date_ |
| Date of repaying original sum loaned. More... | |
| double | principal_ |
| Principal of bond. More... | |
| double | coupon_ |
| Coupon paid by bond. More... | |
| InterestRate | rate_ |
| Interest rate convention. More... | |
| CashFlowVector | cash_flows_ |
| Cash Flow Vector containing julian::FixedCashFlow. More... | |
| Frequency | payment_frequency_ |
| Frequency of coupon payment. More... | |
Friends | |
| std::ostream & | operator<< (std::ostream &, FixedIncomeBond &) |
| Overloads stream operator. More... | |
Detailed Description
Class implements the bond paying fixed coupon.
A fixed coupon bond is represented by julian::CashFlowVector containing FixedCashFlow. Other data is provided just for information purposes only.
More information see [6]
- Examples:
- bondsExample.cpp.
Constructor & Destructor Documentation
|
inline |
Default Constructor.
|
inline |
Constructor.
|
inlinevirtual |
destructor
Member Function Documentation
|
overridevirtual |
virtual copy constructor
Implements julian::Bond.
| double julian::FixedIncomeBond::getCoupon | ( | ) | const |
returns the coupon
|
overridevirtual |
returns the bond's maturity
Implements julian::Bond.
|
overridevirtual |
returns the bond's principal
Implements julian::Bond.
|
overridevirtual |
prize bond
- Parameters
-
curve Interest rate curve used to discount CFs
- Returns
- price of bonds
Implements julian::Bond.
|
overridevirtual |
prize bond
- Parameters
-
curve Interest rate curve used to discount CFs
- Remarks
- second curve is not used
- Returns
- price of bonds
Implements julian::Bond.
|
overridevirtual |
bond valuation
- Parameters
-
curve Interest rate curve used to discount CFs
Implements julian::Bond.
- Examples:
- bondsExample.cpp.
|
overridevirtual |
Friends And Related Function Documentation
|
friend |
Overloads stream operator.
This overloaded operator enables to print the curve on the console.
Member Data Documentation
|
private |
Cash Flow Vector containing julian::FixedCashFlow.
|
private |
Coupon paid by bond.
|
private |
Frequency of coupon payment.
|
private |
Principal of bond.
|
private |
Interest rate convention.
The documentation for this class was generated from the following files:
- C:/Unix/home/OEM/jULIAN/src/instruments/bonds/fixedIncomeBond.hpp
- C:/Unix/home/OEM/jULIAN/src/instruments/bonds/fixedIncomeBond.cpp